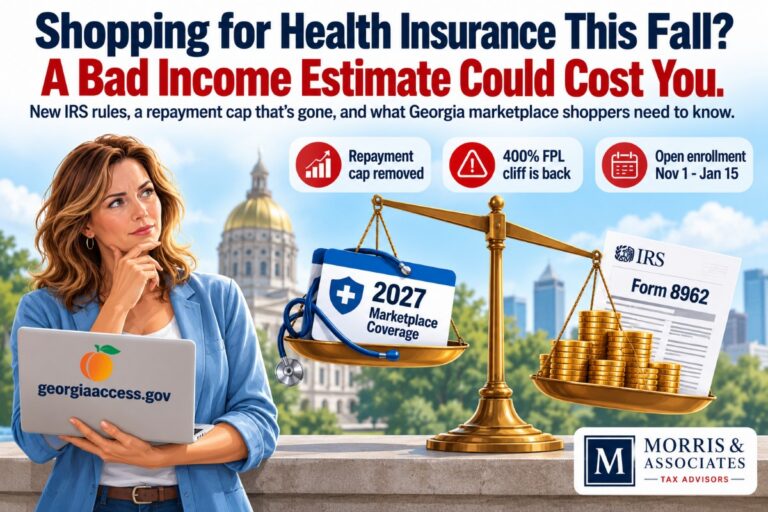
If you buy your own health insurance through the marketplace — rather than getting it through an employer — the next few weeks matter more than usual. Open enrollment for 2027 coverage is about to begin, the IRS just issued new rules for the tax credit that makes marketplace coverage affordable, and a protection that used to limit how much you could owe at tax time is gone. Here’s what Georgia residents need to understand before they enroll.
What the Premium Tax Credit Is
The Premium Tax Credit is a refundable federal tax credit that lowers the cost of health insurance purchased through a marketplace. In Georgia, that marketplace is Georgia Access, the state-run exchange that replaced HealthCare.gov for Georgians in 2024.
Most people don’t wait until tax time to get the credit. They take it in advance — the marketplace estimates what you qualify for based on the income you project for the coming year, and sends that amount directly to your insurer each month to reduce your premium. That’s called the advance premium tax credit, or APTC.
Then, when you file your tax return, you reconcile. The IRS compares what you actually earned against what you estimated. If you earned less, you get additional credit. If you earned more, you have to pay some of it back. That reconciliation happens on Form 8962, using the Form 1095-A your marketplace sends you each January.
What Changed This Week
On October 14, the Department of the Treasury and the IRS issued proposed regulations implementing the Premium Tax Credit changes in the One Big Beautiful Bill Act. The rules tighten eligibility verification beginning in 2027, restrict the credit to U.S. citizens, nationals, and certain lawfully present noncitizens, and add new verification requirements before advance payments go out. Plans purchased through certain income-based special enrollment periods will also no longer qualify for the credit unless tied to a qualifying life event.
These are proposed rules, with a public comment period running through late November and a hearing scheduled for December 8. But the underlying law is already in effect, and the marketplaces are building their 2027 enrollment systems around it.
The Change That Affects Your Tax Return
The new eligibility rules are getting the headlines. But the change that will cost the most Georgia families money at tax time happened quietly, and it’s already in effect.
Through tax year 2025, if your income came in higher than you estimated, the amount you had to repay was capped — anywhere from $750 to $3,150 depending on your income and filing status, as long as you were under 400% of the federal poverty level. A bad estimate was a manageable surprise.
Starting with tax year 2026 — the return you’ll file this coming spring — that cap is gone. If the marketplace paid more credit on your behalf than your actual income supports, you repay the entire difference. There is no ceiling.
For a family that received several hundred dollars a month in advance credit and then had a better-than-expected year — a bonus, a second job, a strong quarter for a self-employed spouse, a retirement account withdrawal — that can mean owing thousands of dollars back to the IRS with the return.
The Subsidy Cliff Is Also Back
There’s a second reason income estimates matter more now. From 2021 through 2025, enhanced credits meant households above 400% of the federal poverty level could still get some help. Those enhancements expired on January 1, 2026, and they have not been renewed.
For 2027 coverage, if your household income lands above 400% of the poverty line — roughly $63,840 for one person, $86,560 for two, and $132,000 for a family of four — you get no credit at all. Not a reduced credit. Nothing. And because the cap on repayment is gone, a household that estimated $80,000 and earned $90,000 doesn’t just lose some of the credit. It pays back all of it.
That’s a cliff, not a slope, and it’s where careful planning pays off.
Why This Is a Tax Planning Problem, Not Just an Insurance Problem
The income number you enter on Georgia Access during open enrollment is, in effect, a number the IRS will hold you to. That makes it a tax decision as much as an insurance decision — and for certain taxpayers, it requires real thought:
- Self-employed and gig workers whose income varies month to month and who may not know what the year will look like until it’s over
- Early retirees who are bridging the gap to Medicare and deciding how much to draw from retirement accounts each year — because IRA withdrawals and Roth conversions count as income for this calculation
- Families near the 400% threshold where a few thousand dollars of extra income could eliminate the credit entirely
- Anyone with a life change coming in 2027 — a job change, a marriage or divorce, a child aging off the plan — that shifts household income or size
For these taxpayers, the question isn’t just “what will I earn?” It’s “how should I structure the year so the number I report is the number I planned for?” That’s tax planning, and it’s worth doing before you enroll, not after you get the 1095-A.
Key Dates for Georgia
Georgia Access open enrollment for 2027 coverage runs through January 15, 2027, and the state has opened its window as early as mid-October in recent years — check georgiaaccess.gov for this season’s exact start date. The date that matters most is December 15, 2026: enroll by then and coverage begins January 1. Enroll after that and coverage starts February 1 at the earliest.
If you’re already enrolled and don’t take action, you’ll generally be renewed automatically — but on last year’s income estimate. Given everything above, that’s a decision worth making deliberately rather than by default.
How Morris and Associates Can Help
The rules around the Premium Tax Credit have gotten more consequential, not less. A good income estimate protects you from a large repayment. A thoughtful year-end plan can keep you on the right side of the 400% threshold. And a correctly prepared Form 8962 — with the 1095-A reconciled properly — keeps your return from being rejected and keeps you eligible for advance credits next year.
At Morris and Associates, Ken Morris meets personally with every client to look at their full income picture — wages, self-employment, retirement withdrawals, investments — and help them make decisions that hold up at tax time. If you buy your own coverage and you’re not sure what income figure to use, or you’ve received a repayment surprise in the past, now is the time to talk, while there’s still time to plan the year.
Contact Morris and Associates today for a free consultation.
Morris and Associates serves individuals and businesses throughout metro Atlanta and across Georgia. Call (678) 641-3193 or visit morristaxadvisors.com to get started.